
What Burger King’s Q3 Sales Rebound Means for Multi-Unit Franchise Operators
The two numbers I’d look at first in Burger King’s third-quarter results are 8.4% and 6,979. The first is U.S. comparable sales growth. The second is the quarter-end restaurant count for RBI’s Burger King reporting segment, down from 7,043 a year earlier. They cover different scopes, but the combination makes an important point for franchise operators. The chain put up stronger sales at comparable U.S. stores even as the segment operated with fewer restaurants overall.
If I were underwriting a group of Burger King locations, I’d want to know where that sales growth came from, which stores still need capital, and what the stores could earn after those investments. The system average gives a buyer a benchmark. The answers come from the restaurants themselves.
Start with the sales mix before pricing a deal
Burger King used Whopper Wednesday and mix-and-match value offers while improving familiar menu items, including the Whopper and chicken nuggets. The U.S. comparable sales increase accelerated from 3.2% in the prior-year quarter to 8.4% in Q3 2026. RBI posted global comparable sales growth of 3.8%, putting Burger King’s U.S. performance ahead of the parent company’s overall result.
For an acquisition, I’d break the sales increase into transactions, average check, and product mix. A store that serves more customers at the same average check has a different staffing and throughput challenge from one that grows primarily through larger orders. I’d also compare promotional weeks with ordinary weeks and check whether the incremental sales generated enough gross profit to cover any extra labor. A sale can improve the top line and still add little to cash flow.
Price the remodel alongside the purchase
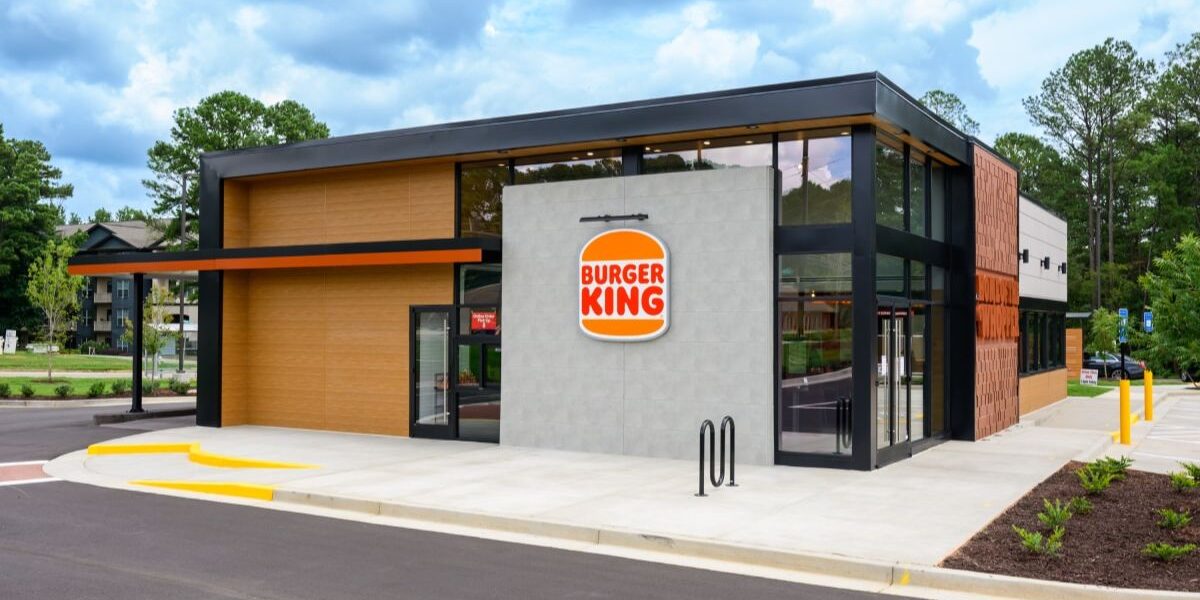
Royal Reset makes the condition of the real estate and equipment particularly relevant. The program can involve changes ranging from building upgrades and kitchen equipment to a full remodel or relocation. RBI had funded US$198 million of up to US$550 million planned for Royal Reset by September 30. That system-level figure gives the program scale. A buyer still needs to establish the scope, timing, and funding terms for each store in the deal.
I’d put the store’s remaining lease term beside its renovation schedule. A location with years of lease control after the work has more time to earn back the investment. I’d also model lost trading days, any temporary drop in sales, and the cash the operator needs while the work is underway. Across several locations, overlapping projects can change the financing picture even when each store looks manageable on its own.
Refranchising puts the focus back on the operator
RBI management also discussed speeding up the refranchising of Burger King restaurants acquired through Carrols in 2024. For a multi-unit group evaluating a portfolio, that raises a practical question about how much management capacity it has to absorb new stores while keeping its existing locations on track.
A cluster of stores can support shared field supervision and give managers a clearer path to advancement. It can also stretch the same leadership team if several restaurants need new general managers or construction at once. I’d value the portfolio on what each restaurant can earn under a realistic staffing and capital plan. Burger King’s stronger quarter improves the backdrop for that analysis. The deal still has to work store by store.
Learn more about Burger King Franchise opportunities.